In this guide
- Supplemental health cover pays a first-year percentage and then renewal commission for a defined number of years.
- The base is the premium collected, so rate increases and mid-year changes move the commission.
- Replacing a plan can reset the client to renewal-level commission rather than first-year.
- Renewal payments that simply stop are the largest silent loss in this product line.
- Cancellations early in the policy year trigger pro-rata corrections.
Contents
Small first year, many renewal years
Supplemental health plans, Medicare Supplement business included, are usually written as annually renewable cover with a modest premium. The commission structure follows that: a first-year percentage that is far lower than on long-term life cover, then renewal commission for a defined number of years.
Two implications:
- No single sale is material. Income comes from volume and from persistency, not from individual cases.
- Renewal years are contractual. Commission often runs for a set number of renewal years and then reduces or stops. If you do not know that number per product, you cannot tell a stopped payment from an expected end.
Model either shape year by year in the commission calculator using a level rate for the renewal years.
The base moves every year
The base is normally the premium collected in the period, and supplemental health premiums are reviewed frequently. So the base changes even when nothing about the plan changes.
Things that move it:
- Annual rate increases by the insurer — the base and the commission rise together.
- Age-banded premiums — the premium moves as the client crosses a band.
- Mid-year plan changes — a switch of plan level changes the premium and possibly the commission year.
- Payment frequency — monthly collection spreads the same annual commission across twelve lines.
Any of these makes a period-to-period comparison of totals meaningless. Compare per policy against your own expected figure instead.
Replacements, switches and the year counter
The detail most often missed in this product line is which policy year the commission is being paid for.
Where a client is moved from one plan to another, the new plan may be treated as a replacement rather than new business. Depending on the contract, that can mean:
- renewal-level commission rather than first-year commission on the new plan;
- the year counter continuing from the old plan;
- no commission at all where the switch is inside the same insurer's family of plans.
None of this is visible on a statement unless you know what to expect, which is why the plan history per client needs to be recorded, not remembered. Policy renewal management covers the record-keeping side.
The check that actually pays for itself
With small amounts and many policies, the loss that matters is not a wrong rate — it is a renewal payment that quietly stops. One missing renewal on one plan is trivial; the same gap across dozens of plans, running for years, is not.
A workable monthly routine:
- Expected renewal commission per active policy for the period.
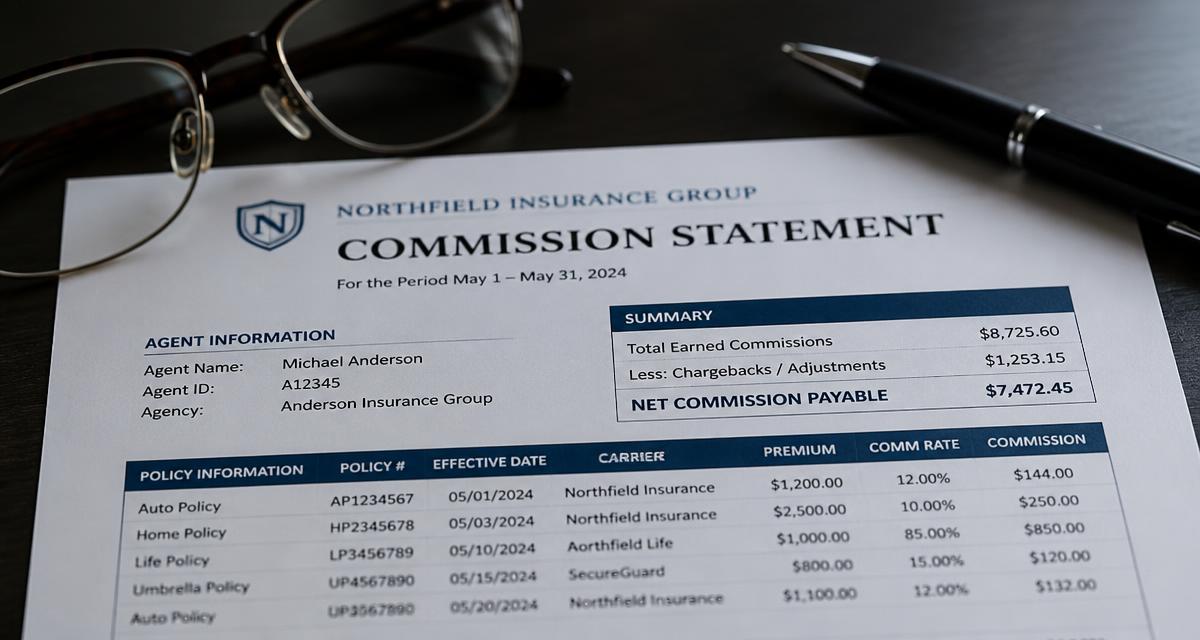
- Match statement lines by policy number.
- List the policies that were expected and not paid.
- List payments that match no policy at all.
- Check corrections against cancellations you know about.
At this volume the routine only survives if it is automatic. That is what Safe Mode is for: it shows only the lines that need a decision, and unmatched commissions collects payments with no matching policy. The free demo runs it on sample health policies, and the reading side is covered in how to read your commission statement.
Frequently asked questions
How is Medicare Supplement commission structured?
Typically as a first-year percentage of the premium followed by renewal commission for a defined number of renewal years. Exact percentages and the number of renewal years are set by the insurer's contract for that plan.
Why did my renewal commission on a health plan stop?
Three common reasons: the contractual renewal years for that plan have ended, the policy lapsed or was cancelled, or the client was moved to another plan and the commission year was reset. Only your own per-policy record can tell you which.
Does a rate increase raise my commission?
Where commission is calculated on the premium collected, yes — a higher premium produces a higher commission at the same percentage.
Does replacing a plan pay first-year commission again?
Often not. Many contracts treat a switch within the same insurer as a replacement and pay renewal-level commission, continuing the original year count. Check the contract before assuming new-business rates.
Try Commission Clarity on your own data
Client records, policy portfolio and commission control in one place. Your data stays in your own Google Sheets — Commission Clarity reads it live and highlights the discrepancies.