In this guide
- A missed renewal costs the premium, the renewal commission and often the client relationship.
- Renewal tracking needs dates, status and owner — a date alone produces no action.
- Policy tracking and renewal tracking are the same job seen from two ends.
- Renewals connect directly to commission: no renewal, no renewal commission line to check.
- Start with one list of every policy and its renewal date before choosing any tool.
Contents
Why renewals slip
A renewal does not announce itself. There is no failed payment on your side, no complaint, no error message. The policy simply lapses, and the loss shows up much later as a smaller commission statement.
Three causes cover most cases:
- The renewal date lives in a document rather than in a list you actually open.
- Nobody owns the follow-up, so it is everyone's and no one's.
- The date is known but the client contact is not prepared, so the conversation happens too late.
The cost of one missed renewal is not one premium. It is the renewal commission for every remaining year the policy would have run.
What renewal tracking has to contain
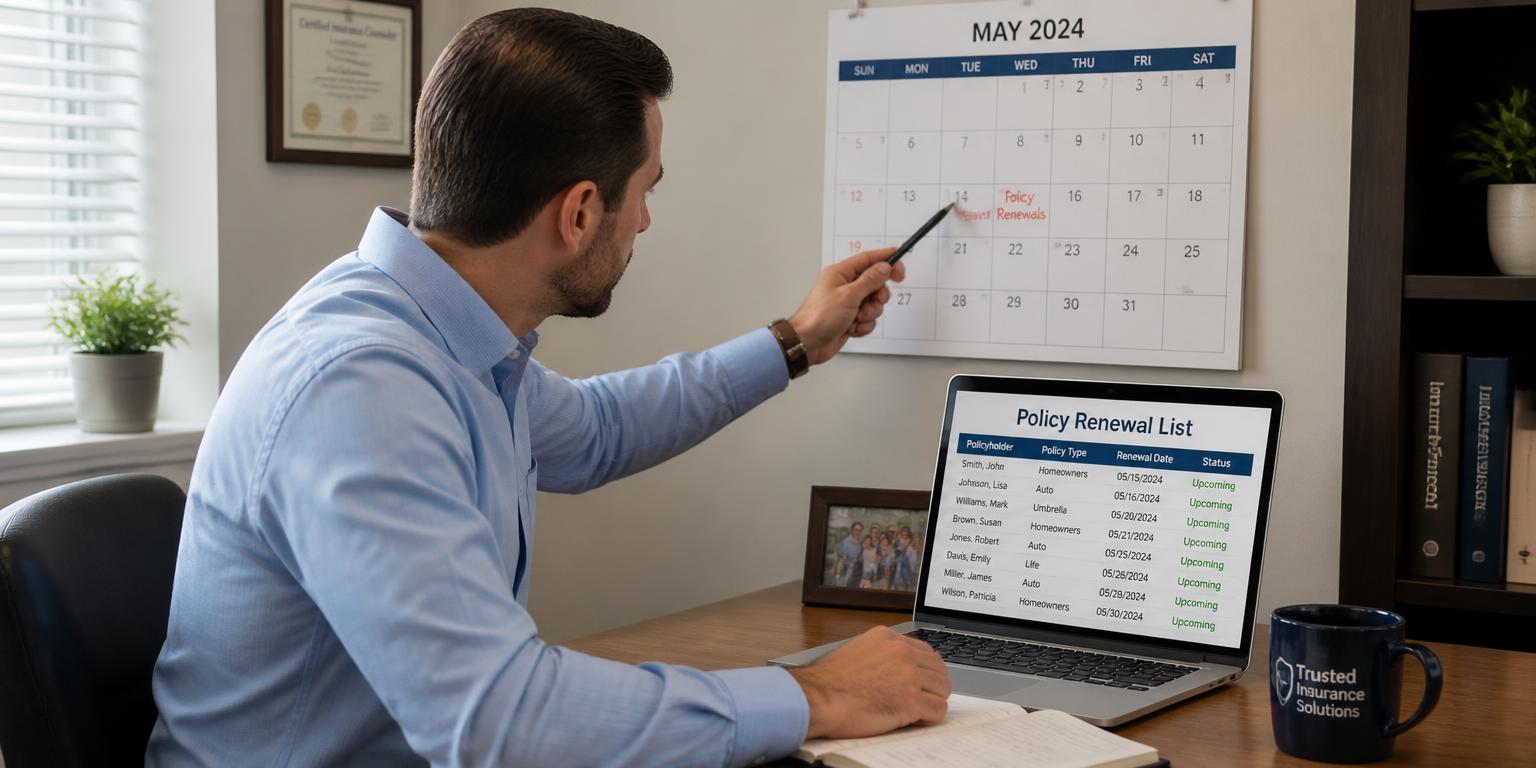
A renewal date on its own produces nothing. A workable renewal record has four parts:
- The date — and the notice period before it, which is the part that actually drives action.
- The status — upcoming, contacted, renewed, lapsed, under review.
- The owner — the person whose list it appears on.
- The policy context — premium, product, insurer and the client's other policies.
That fourth part is what turns a renewal into a conversation rather than an administrative reminder: you can see what else the client holds before you call.
Policy tracking and renewal tracking are one job
People search for renewal tracking software and policy tracking software separately, but the underlying record is the same: one row per policy, with dates, status and premium.
Once that record exists, renewals are a filtered view of it. So are lapses, policies under review, and the portfolio total. If you are evaluating tools, check the policy record first — if it is thin, every view built on it will be thin too.
Commission Clarity keeps that record in your own policy portfolio and reads it from the data you already maintain. The practical detail of setting it up is in policy record keeping.
Renewals and commission are the same money
Renewal commission is usually a smaller percentage than first-year commission, paid for every year the policy stays in force. Over a long book it often becomes the larger share of income.
That has two consequences worth acting on:
- A lapsed policy removes a future income line, not just a one-off payment.
- A renewed policy creates an expected commission figure you should then check against the statement — because renewal lines are the ones most often quietly missing.
You can model that income over the policy term with the free commission calculator, and see the checking side in the Commission Monitor.
How to start this week
You do not need software to fix the first 80 per cent of this.
- Build one list of every active policy with its renewal date and premium.
- Sort by date and mark the next 60 days.
- Assign each one an owner, even if that is only you.
- Decide the notice period you want — a fixed number of days before renewal.
- Only then ask what a tool should automate.
The tool earns its place when the list grows past what you can scan, when more than one person works from it, or when you want renewals connected to the commission they produce. You can try that connected view with sample data in the free demo.
Frequently asked questions
What does insurance renewal software do?
It keeps every policy's renewal date, notice period, status and owner in one place, flags what is coming due or already lapsed, and connects each renewal to the premium and commission attached to it.
Is renewal tracking different from a calendar reminder?
A reminder tells you a date arrived. Renewal tracking also tells you the status, who is handling it, what the client already holds and what income depends on the outcome.
How far in advance should renewals be flagged?
Choose a fixed notice period and apply it consistently. The exact number matters less than having one rule, because an inconsistent notice period is why some renewals are handled late.
Do missed renewals affect commission?
Yes. A lapsed policy stops producing renewal commission for every remaining year of the term, so a renewal problem shows up later as a commission problem.
Try Commission Clarity on your own data
Client records, policy portfolio and commission control in one place. Your data stays in your own Google Sheets — Commission Clarity reads it live and highlights the discrepancies.