In this guide
- Agent income is rarely a single figure: first-year commission, renewal commission and overrides are calculated differently.
- Commission is normally a percentage of premium, so the premium base decides the payment more than the rate does.
- Renewal commission is smaller per policy but compounds across a portfolio.
- Overrides pay a manager or mentor a share of someone else's production.
- Every part of the calculation is checkable if the expected amount is recorded when the policy is written.
Contents
The four parts of an agent's income
Most agents are paid from a combination of components rather than one rate. Separating them is the first step to checking any of them.
1. First-year (acquisition) commission
Paid when a new policy is written, calculated as a percentage of the premium. It is the largest single payment per policy and the one most agents check.
2. Renewal commission
Paid for each subsequent year the policy stays in force. Smaller per policy, but it accumulates across a portfolio and requires no new sale. It is also the payment least likely to be noticed when it fails to arrive.
3. Overrides and shares
Where an agency, team leader or mentor receives part of the commission on production written by someone else. The share is normally set per product line, not as one flat number.
4. Adjustments and clawbacks
Negative entries: a cancelled policy inside the clawback period, a corrected premium, an unpaid instalment. These reduce a payment that was already made and are covered in detail in commission clawbacks.
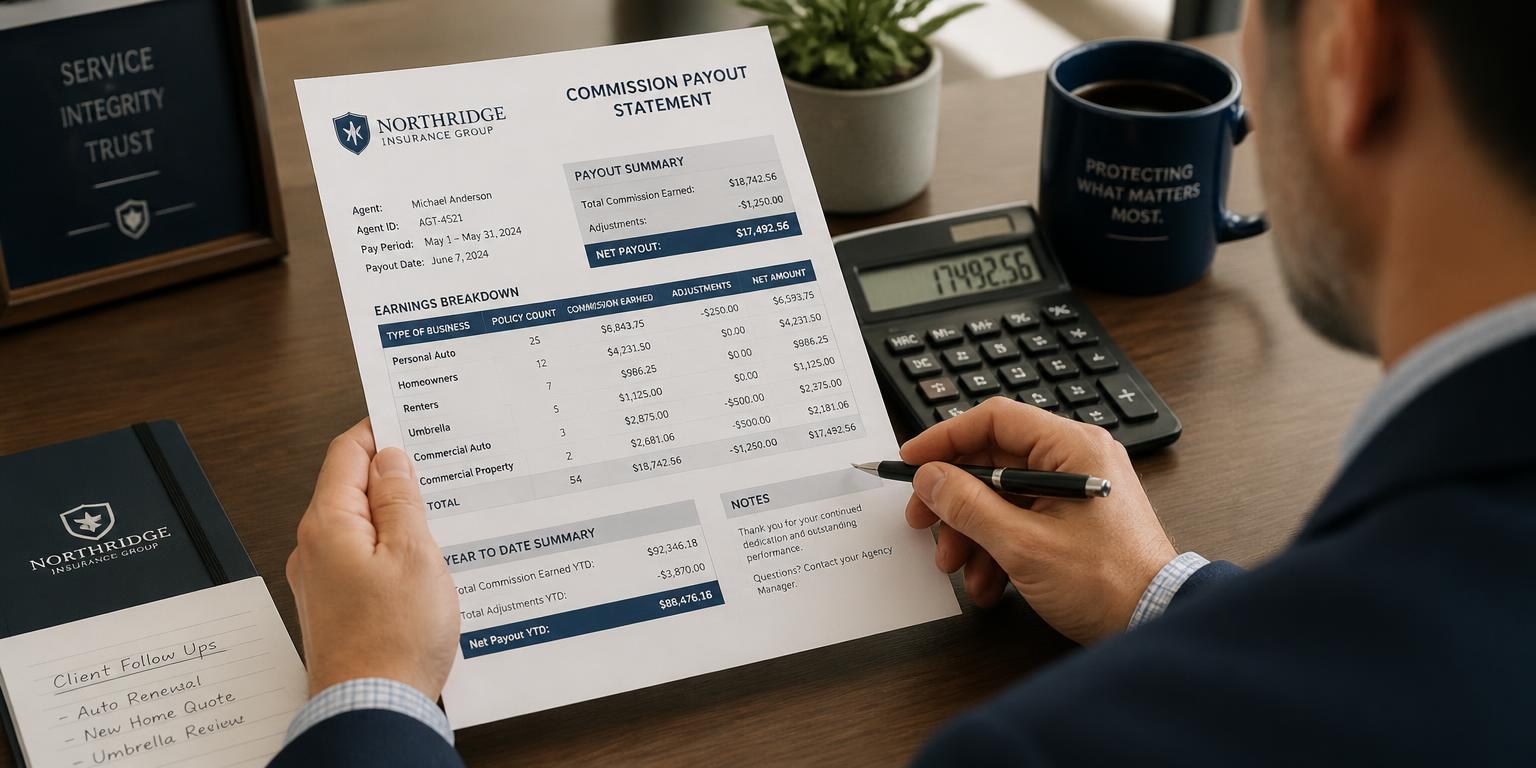
A payment slip showing one net figure is the sum of all four. Without the breakdown, a missing renewal and a routine adjustment look identical.
How the calculation actually works
Commission is a percentage of a premium base. Both halves of that sentence matter.
The rate
Your agreement sets a rate per product, and often per premium band or payment frequency. Two policies with the same premium can pay different amounts because they sit under different rules.
The base
The rate is applied to a specific base: annual premium, first-year premium, or premium actually collected. This is where most disputes begin, because the base on the statement and the base in the agreement are not always the same thing.
A worked example
- Annual premium: 600.
- Agreed rate for that product: 12%.
- Expected commission: 72.
- Payment received: 61.20 — a 15% shortfall with no explanation on the statement.
Nothing on the statement flags that difference. It only appears when the expected 72 was recorded at the moment the policy was written.
Why the expected figure has to be stored
Recalculating expectations from memory a year later is not realistic across hundreds of policies. Storing the expected amount per policy turns commission checking into a comparison instead of an investigation. That is exactly what the commission monitor does with the data an agent already keeps.
Why renewal commission is the weak point
Renewal income has a structural problem: nobody is waiting for it.
A new policy has a date, a client conversation and an expected payment in mind. A renewal in the fourth year of a policy has none of those. If the payment simply does not appear, there is no moment at which anyone notices.
What goes wrong in practice
- the policy renewed but was not included in the payment run,
- the payment was made to a different agent code after an internal change,
- the premium changed and the commission was calculated on the old base,
- an instalment went unpaid and the commission was reversed without a visible entry.
The only reliable check
Compare the list of policies that renewed in a period against the commission lines received for that period. Anything on the first list without a match on the second is either a genuine exception or lost income — and both need an answer. The method is set out step by step in how to check your commissions, and renewal timing itself in policy renewal management.
When income is split with an agency or mentor
Inside an agency, the commission the provider pays is rarely what the individual agent receives. It is divided.
Typical structures
- A flat share: the agent receives an agreed percentage of the commission on their own production.
- A per-product share: different splits for different lines of business, which is the more common arrangement in practice.
- A mentor or team override: a third party receives a share of a newer agent's production, usually for a defined period.
Why per-product splits need to be written down
A single agency-wide percentage is easy to remember and almost never accurate. Once splits differ by product, the only workable approach is to store the split alongside the commission rules themselves, so the agent's share is calculated from the same figures the provider used.
The full mechanics of splits, mentors and overrides are covered in agency commission splits.
An agent who cannot reproduce their own split calculation cannot check it. That is a reporting problem, not a trust problem.
A routine that keeps income honest
The point of understanding the structure is being able to verify it without spending a weekend on it.
Monthly, in under an hour
- Import the statement lines for the period.
- Match each line to a policy.
- Compare received against expected per policy.
- Deal with three lists only: shortfalls, missing payments, and statement lines that match no policy.
What to do with a discrepancy
Raise it with a specific reference: the policy number, the premium base you used, the rate from the agreement, and the difference. A query framed that way is answered; a query saying "this looks low" usually is not. Your entitlement to the payment itself is covered in the right to commission.
Where to start if none of this is recorded today
Start with the records you already have. Most agents keep policies in a spreadsheet, which is enough to build expected amounts from — see Google Sheets client records. If you would rather see the arithmetic on your own numbers first, the commission calculator does a single policy in a minute, and the demo shows the full comparison on sample data.
Frequently asked questions
How do insurance agents get paid?
Almost always by commission calculated as a percentage of the premium on the policies they place, paid by the insurance provider rather than by the client. Employed agents may also receive a salary, and some agencies pay a fee per case, but percentage-of-premium commission is the standard structure.
How much does an agent earn per policy?
It depends on the line of business, the premium and the specific agreement, so any single figure would be misleading. What matters practically is that your own agreement states a rate per product, and that rate applied to the actual premium gives the amount you should be paid.
Is renewal commission paid automatically?
It should be, but it is the payment most often missing. A renewal that goes through without a corresponding commission line looks like nothing at all unless you compare received payments against the policies that renewed.
What is an override?
A share of the commission from another person's production, usually paid to an agency, a team leader or a mentor. It is calculated from the same premium base, so an error in the underlying policy affects everyone in the chain.
Try Commission Clarity on your own data
Client records, policy portfolio and commission control in one place. Your data stays in your own Google Sheets — Commission Clarity reads it live and highlights the discrepancies.