In this guide
- Recording payouts is bookkeeping; comparing them against your own rules is control.
- The core requirement is a per-policy expected figure calculated from your commission agreement.
- Unmatched statement lines matter as much as discrepancies — they are where money disappears quietly.
- Clawbacks need their own treatment, otherwise a reversal looks like a normal negative entry.
- Test any tool with one real statement before you commit to it.
Contents
Tracking versus control: the distinction that decides everything
Most tools sold as commission trackers do one job: they store the amounts an insurer reported and total them by month, product or insurer. That is useful for tax and planning, and it is useless for finding errors, because the figure being reported is the figure being checked.
Two different questions
- Tracking answers: how much commission did I receive this quarter?
- Control answers: how much should I have received, and what is missing?
Only the second question can find an unpaid renewal commission, a rate applied at the wrong level or a clawback taken twice.
If a tool cannot state an expected amount independently of the statement, it cannot detect an error in that statement. It can only add the errors up.
Why this gets overlooked
Expected commission requires your own agreement to be encoded as rules. That is a setup step providers prefer to avoid, because it takes effort and differs for every agent. Tools that skip it look simpler in a demo and never find a cent.
Core requirements to insist on
Five capabilities separate a control tool from a ledger.
1. Commission rules you define yourself
Rates by insurer, product and policy year, with a distinct rate for the first year and for renewals, and support for a rule changing on a date without rewriting history.
2. A per-policy expected amount
Calculated from those rules and the policy's premium and payment frequency, for each period — not a portfolio-level estimate.
3. Line-level matching
Each statement line matched to a policy. A monthly total that agrees hides two errors cancelling each other out.
4. A discrepancy list with categories
Missing payout, underpayment, overpayment, clawback, duplicate. Categories matter because each one needs a different conversation with the insurer.
5. Unmatched items kept visible
Lines that could not be matched to any policy in your portfolio must stay on a list until resolved. Anything discarded silently is a permanent blind spot — this is what the unmatched commissions view exists for.
Useful, but secondary
- income projections from the portfolio in force,
- income by insurer and product,
- export for your accountant,
- a history of rule versions.
Clawbacks need their own handling
A clawback is a reversal of commission already paid, usually because a policy lapsed or was cancelled inside a defined period. Handled as a plain negative amount, it becomes almost impossible to check.
What the software has to show
- Which policy the reversal relates to.
- Which original payout is being reversed, and from which period.
- The proportion reversed, against the rule that governs it.
- Whether the reversal was already taken in an earlier statement.
- The running balance per policy, so a double reversal stands out.
The error pattern worth watching
Repeated partial reversals across several statements. Each one looks small and plausible; together they can exceed the commission originally paid. Without a per-policy balance nobody notices.
For the mechanics of how clawbacks arise and what limits apply, see the guide on commission clawbacks.
What a working monthly routine looks like
Software only helps if it fits into a routine short enough to survive a busy month.
The routine, in four steps
- Import the statement as soon as it arrives, without retyping it.
- Review the discrepancy list, which should be short if the rules are right.
- Resolve unmatched lines, either by correcting the portfolio or by querying the insurer.
- Send one consolidated query per insurer, with policy numbers, periods, expected amounts and the rule you are relying on.
How long it should take
For a portfolio of a few hundred policies, twenty to thirty minutes a month once the rules are configured. If it takes longer than that, the matching is doing too little and you are doing too much.
A monthly review that takes half an hour gets done. A quarterly review that takes a day gets postponed until the documentation is gone.
The step-by-step method behind this routine is set out in how to check your commissions.
How to test a tool before you commit
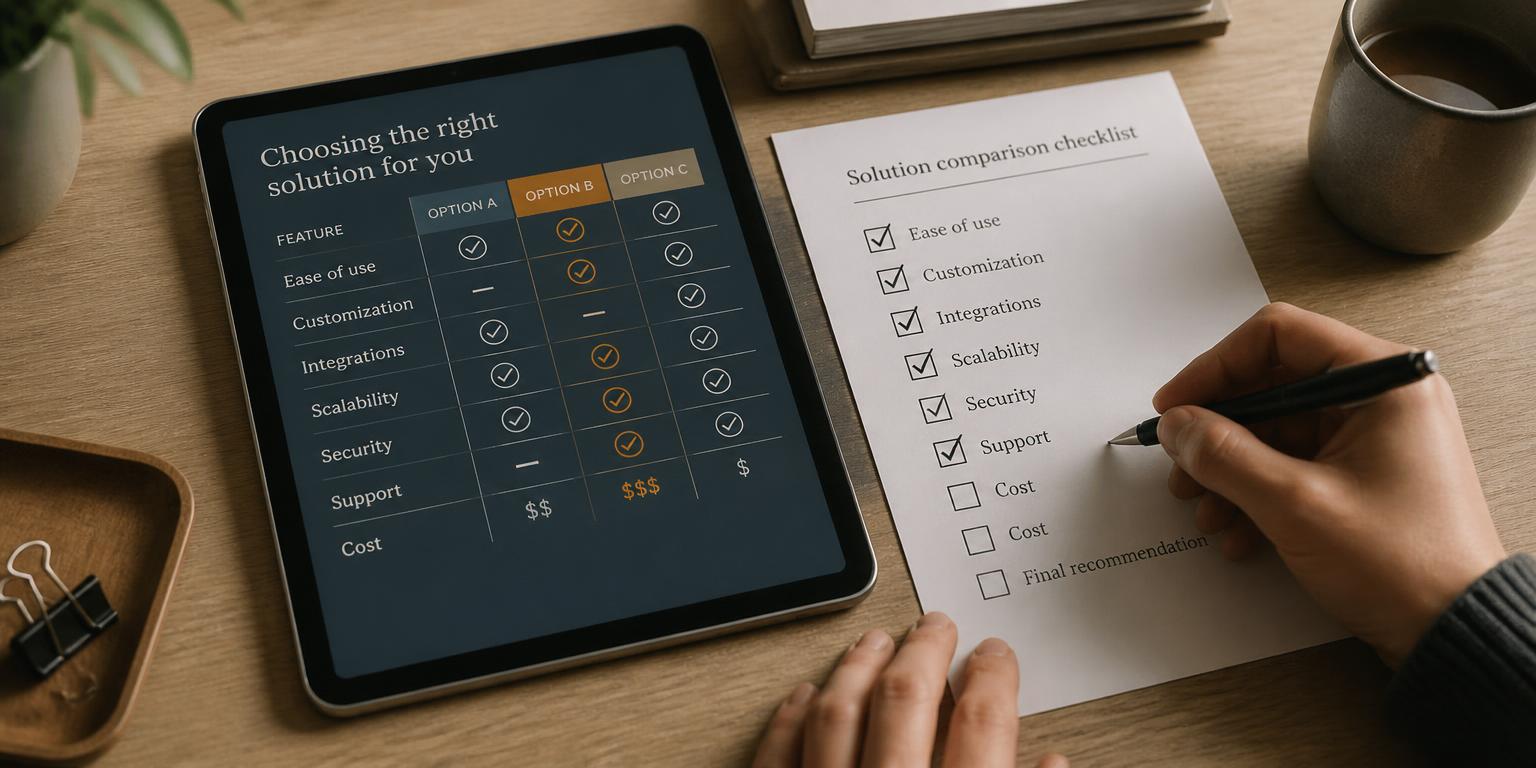
One real statement tells you more than any feature list.
The test
- Take the most recent statement from your largest insurer.
- Configure the commission rules for the two or three products it covers.
- Let the tool import and match the statement.
- Compare its discrepancy list against a manual check of ten policies you pick yourself.
What a good result looks like
- Every line matched, or explicitly listed as unmatched.
- Discrepancies you can explain, each tied to a rule and a policy.
- No manual retyping at any point in the process.
- The same check repeatable next month in minutes.
Warning signs
- The tool only accepts data in its own template.
- Expected commission has to be entered by hand per policy.
- Unmatched lines are dropped without a trace.
- Rule changes overwrite history, so past periods silently recalculate.
If you want to see the workflow before setting anything up, the demo account runs on sample data with discrepancies already in it.
Frequently asked questions
Is a spreadsheet enough for tracking commissions?
A spreadsheet is a good record and a poor control. It will hold what was paid, but recalculating expected commission per policy and per period by hand stops happening as soon as the portfolio grows past a few dozen policies.
What is the difference between tracking and reconciliation?
Tracking records payouts. Reconciliation matches each statement line to a policy in your portfolio, compares it against the expected amount, and leaves a list of items that did not match. Only the second one finds errors.
How far back is it worth checking?
Start with the last twelve months, because that is where documentation is still easy to obtain and a claim is still practical. Once the rules are set up, older periods can be recalculated at no extra effort.
Try Commission Clarity on your own data
Client records, policy portfolio and commission control in one place. Your data stays in your own Google Sheets — Commission Clarity reads it live and highlights the discrepancies.